01
Shared workspace for AI coding agents.
Connects briefs, code, decisions, and running previews so agents and engineers can work from the same project context.
AI infrastructureMichael Becker · Founder-side M&A
Selective mandates · private process
I help founders sell what they’ve built. I prepare the acquisition case, approach specific strategic buyers, and represent you through diligence, negotiation, and close.
Core focus: $1M–$5M ARR Select earlier-stage technology & IP
Direct conversations with strategic buyers
Acquisition-related correspondence with corporate development and product leaders across B2B software and AI. I choose the buyer for fit, then find the best route in.
Current M&A representation
A selective portfolio across AI, developer tools, enterprise software, healthcare, and sports technology. Each mandate has its own buyer case and private sale process; public descriptions keep company identities confidential.
Connects briefs, code, decisions, and running previews so agents and engineers can work from the same project context.
AI infrastructureAI and immersive-training IP that turns sports performance data into coaching, analytics, and fan experiences.
Sports technologyA purpose-built communication and workflow product designed for teams that live on mobile.
Mobile SaaSProcess intelligence that reads how business systems are used, finds friction, and reveals automation opportunities.
Process intelligenceA production-ready engine that detects consequential deviations before they become commercial or operational exposure.
Legal technologyA developer platform that analyzes application repositories, generates deployment configurations, and automates cloud provisioning, routing, and monitoring.
Developer infrastructureAI-assisted revenue-cycle management: denial analysis, work allocation, analyst review, and reporting. Operational outcomes await pilot validation.
Healthcare softwareA running-health app combining expert videos, structured injury and rehabilitation programs, and application-specific AI configurations.
Running & recoveryConfidentiality protocol Public descriptions intentionally exclude company names, valuation expectations, buyer activity, transaction terms, and sensitive product detail. Qualified parties receive fuller materials through a confidential review path.
My sweet spot is founder-led software and AI companies generating roughly $1M–$5M ARR. I also consider companies approaching $10M ARR and select pre-revenue technology and IP assets with compelling strategic buyer value.
SaaS and AI businesses with recurring revenue, customer proof, and a product a strategic acquirer can extend.
Working products, code, patents, data, prototypes, and technical systems with clear strategic buyer value.
Venture-studio companies, portfolio assets, dormant products, and founder-owned IP ready for a dedicated owner.
M&A advisor, broker, or marketplace
Founders searching for a pre-revenue M&A broker, pre-revenue M&A agent, early-stage M&A broker, sell-side M&A advisor, or startup acquisition advisor will encounter very different models. I provide direct founder-side M&A representation for software, AI, and IP assets whose best buyers are specific strategic acquirers rather than a broad marketplace audience.
A SaaS M&A advisor or SaaS M&A broker fits recurring-revenue companies where growth quality, retention, margins, customer concentration, and strategic buyer appetite shape the outcome.
A software M&A advisor or technology business broker can fit standardized, profitable businesses. Differentiated or pre-revenue software often requires narrower representation built around named strategic acquirers.
The buyer may be acquiring code, IP, customers, data, a team, a product wedge, or years of development time. The sale process should explain exactly which.
About Michael
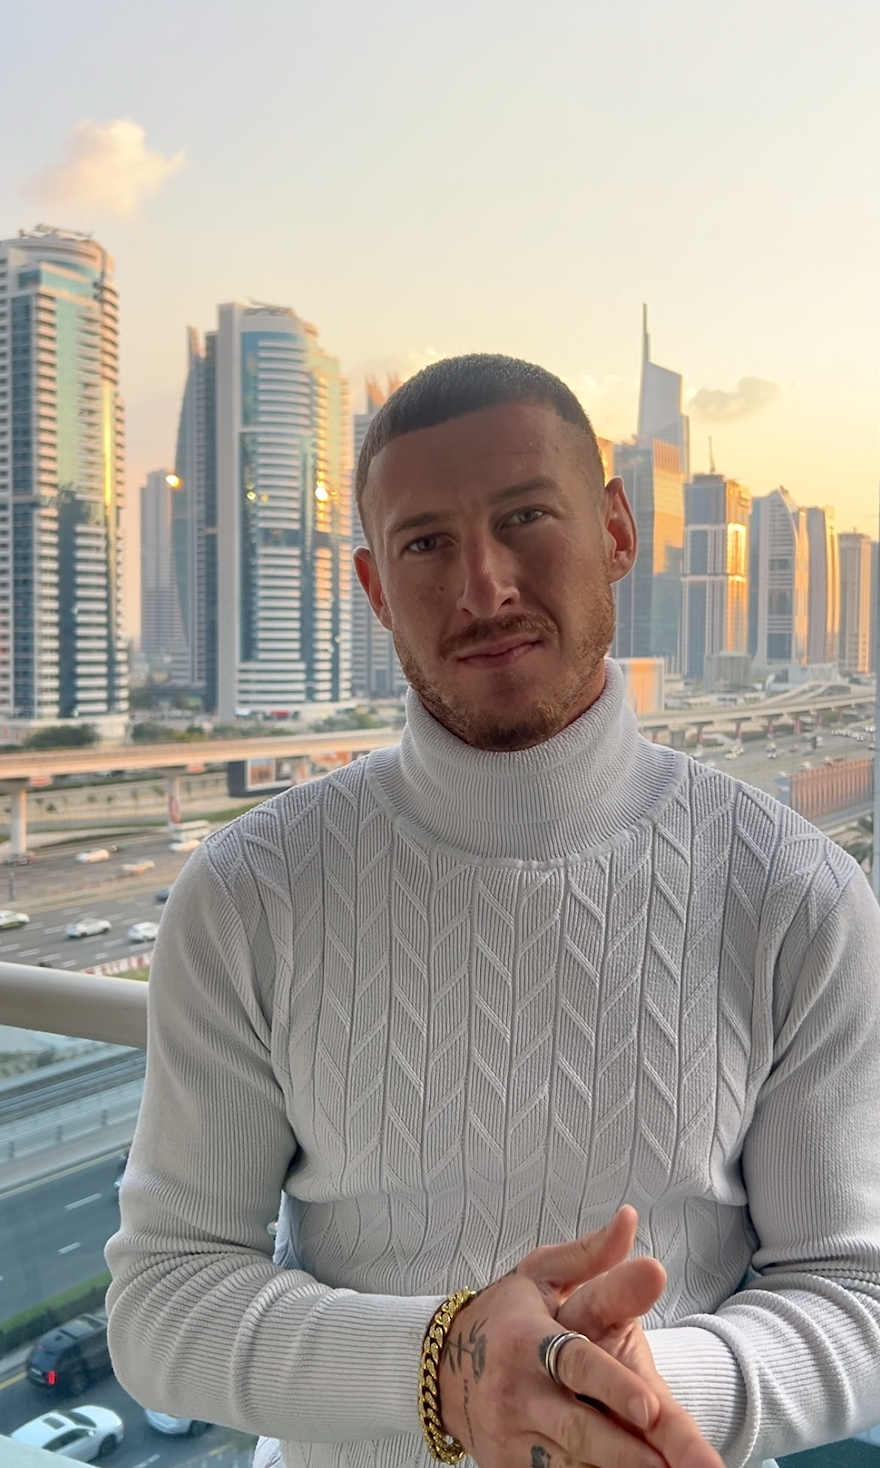
Michael Becker · Founder-side M&A representative
I spent 12 years inside software, SaaS, AI, and GTM, including three businesses moving through acquisition environments: Emarsys before SAP, Teradata Applications before its divestiture, and SharpenCX during the investment period preceding its acquisition. In 2023, I sold a pre-revenue media asset I had built myself.
That founder exit changed the direction of my work. I found the role I cared about most: identifying where a product creates disproportionate value, earning the right buyer’s attention, protecting leverage, and advocating for the strongest credible outcome. Today, I carry eight sell-side mandates personally and act as the founder’s acquisition representative from strategy through close.
Every accepted mandate stays with me. I conduct the research, shape the buyer thesis, create the acquisition materials, make the approach, and stay with the founder through diligence, offers, and closing.
The transaction figures describe companies where Michael worked and the scale of those acquisition environments. They represent operating context rather than advisory tombstones.
Why Michael Becker
When you work with me, you get me. I review the product, develop the buyer case, create the materials, lead outreach, and stay with the conversations through diligence, negotiation, and close. You get a direct assessment of buyer interest and whether the next step is worth taking.
I research each strategic acquirer’s roadmap, product gaps, customers, acquisition history, and likely internal sponsor before outreach begins. The approach can include a tailored brief, Loom, mockup, or product concept built for that buyer.
My work across SaaS, AI, GTM, Antler, SAP, and multiple acquisition environments informs which positioning will travel, which buyers can act, and where transaction risk will appear.
I pressure-test ownership, product proof, technology, dependencies, transferability, and likely buyer objections before outbound M&A outreach begins.
Each strategic buyer receives research and acquisition materials built around its products, roadmap, customers, and acquire-versus-build case.
Research, materials, revisions, outreach, and founder communication stay with one accountable advisor, allowing the mandate to move quickly.
The exclusive M&A mandate
Every accepted M&A representation engagement is selective, exclusive, and private. I manage the strategy, buyer preparation, outreach, diligence, offers, and closing path directly.
Confirm the legal entity, IP ownership, transferable assets, product proof, seller expectations, timing, and likely buyer interest.
Define what the acquirer receives, the acquire-versus-build logic, a defensible value range, and the likely internal sponsor.
Build the confidential buyer brief, tailored assets, diligence foundation, management narrative, and buyer conversation path.
Approach a named buyer universe one-to-one with personalized M&A outreach tied to each acquirer’s roadmap and priorities.
Manage buyer interest, meetings, information flow, competitive tension, transaction diligence, offers, negotiations, and closing.
Before outreach, we agree the outcome you want, what you would accept, your transition role, and what buyers can see. I manage the process and keep you informed; you bring product knowledge, timely answers, and decisions. If feedback calls for a different buyer group, stronger evidence, or a pause, we reassess together.
Relevant experience
My M&A perspective comes from operating inside software businesses before and during changes in ownership, plus building and selling a pre-revenue asset of my own.
Built the content and editorial engine across five years preceding SAP’s acquisition.
Reported $500MWorked inside the applications business before its divestiture.
Reported $90MOperated inside the company during the strategic investment period preceding its acquisition.
Pre-acquisitionBuilt, operated, and sold a founder-owned pre-revenue digital media asset through Flippa.
Founder exit · 2023Eight current mandates across AI, developer tools, enterprise software, healthcare, and sports technology. Prior representation included XR Upgrade, a European SaaS-and-services company, and ChatDoctor, a privately owned U.S. software asset.
Founder-sideReported transaction figures provide operating context. They describe company-level outcomes in environments where Michael worked rather than sell-side advisory tombstones attributable to him.
A letter to founders
The work, the fees, your role, and an honest view of what a sale process can—and cannot—promise.
Questions founders ask
My preferred range is approximately $1M–$5M in annual recurring revenue (ARR), with scope up to roughly $10M ARR. I work with founder-led SaaS, AI, and software companies where a specific buyer could gain a useful capability, customer connection, or product advantage through an acquisition.
I also selectively represent pre-revenue technology and software IP. A working product, meaningful technical depth, clear ownership, and a credible acquire-versus-build case matter more than an ambitious asking price. Sometimes a paid deployment or ownership cleanup is the better next step before a sale process.
An initial review covers the product, users, revenue, ownership, timing, previous buyer conversations, and the outcome you would accept. I also consider whether the likely proceeds, fees, and work make an engagement worthwhile for both of us.
I start with what is actually being acquired: the company, a product, selected code and IP, customer relationships, or technology with a team joining the buyer. Then I assess the commercial evidence and what a specific acquirer could reasonably gain by owning it. For a recurring-revenue business, growth quality, retention, margins, concentration, and operating costs help establish the picture.
Earlier-stage software often needs a more specific case: difficult engineering already completed, a working implementation, useful IP, or development time the buyer could save. Asking price and effort invested are not enough on their own. Relevant transaction comparisons can inform the discussion where reliable data exists; a generic multiple rarely explains the whole opportunity.
We also compare payment structures. Cash at closing, deferred payments, earnouts, equity, and founder obligations can make similar headline prices very different outcomes. My work develops commercial valuation logic, rather than a formal valuation opinion.
A clear reason to acquire. The product should help the buyer do something it already cares about: launch sooner, fill a product gap, reach relevant customers, or add a difficult-to-reproduce capability. We need to explain why buying makes sense compared with building, partnering, or leaving the problem alone.
Buyers also need evidence they can examine. That may include a reproducible demo, customer and revenue records, usage, architecture, operating costs, and technical documentation. For AI products, model-provider dependencies, data rights, evaluations, and the distinction between proprietary work and third-party services deserve particular attention.
Finally, the transfer must be workable: ownership, contributor assignments, licenses, consents, customer obligations, and a realistic handover. We distinguish what works today from planned features, proposed integrations, and modeled outcomes before a buyer has to discover those limits independently.
I use an initial 60- or 90-day campaign as a working window where appropriate; the engagement agreement sets the actual term. That is time to prepare the asset, test buyer fit, conduct outreach, and develop serious conversations. It is not a promise to close within that period.
A transaction can take longer as product reviews, internal sponsorship, budget, approvals, diligence, commercial terms, and legal documents come together. A small purchase by a large company can move slowly if nobody owns the internal case. A smaller, well-capitalized operator with clear authority may sometimes be a more practical buyer.
We review progress against actual buyer responses and next steps. If the evidence points to a different buyer group, better preparation, or stopping the process, I will say so. Continuing should have a reason beyond simply extending the timetable.
A full sell-side mandate usually includes a defined period of exclusivity. I am committing personal time to product review, materials, research, and outreach before a buyer engages. A coordinated process also helps protect confidential information, keep buyer communication consistent, and avoid competing approaches to the same company.
Before we start, we identify existing buyer conversations and agree how they will be treated. The written agreement covers the engagement term, seller responsibilities, documented carve-outs, independently sourced transactions, termination rights, and any fee protection after the engagement ends.
Exclusivity should be something you understand before signing. Review the terms with counsel, including which transactions attract a fee and what obligations continue afterward. If a founder, investor, or another advisor already has a live conversation, tell me before new outreach begins.
I start with strategic fit and the practical ability to complete a worthwhile purchase: product priorities, customer overlap, integration requirements, acquisition behavior, a likely internal sponsor, and a credible path to a decision. A famous logo or a large balance sheet does not make a company the right buyer.
The route in may be a corporate development contact, product leader, CTO, founder, or an introduction from your own network. The depth of my relationships varies. I choose the buyer for fit, then work out the strongest way to approach them; an invitation to share opportunities is not the same as interest in your company.
Outreach is tailored and managed in staggered waves. Selected approaches may include a concise brief, Loom walkthrough, private acquisition page, or clearly labeled integration concept. We agree disclosure limits before sharing sensitive materials, and use real responses to refine the case and subsequent outreach.
No. A sale depends on a buyer wanting the opportunity, being able to act, completing diligence, and agreeing acceptable terms. Early-stage and commercially unproven software can be exceptionally difficult to sell. Even a capable advisor, distinctive technology, and serious conversations may produce no offers or completed transaction.
You are paying for the agreed work and committed time, with that possibility understood. My contribution is a specific acquisition case, relevant routes into buyers, tailored outreach, candid feedback, and persistent management of the process. I will distinguish polite replies, exploratory conversations, diligence, and an actual offer.
If interest is weak, we examine why: price, timing, strategic fit, implementation, or the buyer's preference to build. We may change the approach, strengthen the evidence, explore another sale scope, or stop. I would rather give you an accurate assessment than keep an unsupported expectation alive.
A pre-revenue M&A broker, M&A agent, or sell-side advisor helps establish whether a software product or IP asset has a credible acquisition case, identifies relevant buyers, prepares materials, coordinates private outreach, and represents the founder through commercial discussions, diligence, offers, negotiation, and closing.
Without a revenue history, the evidence may rest on a working implementation, technical depth, owned IP, a specialist team, or a capability a buyer could deploy sooner than it could build. We define what transfers, the dependencies a buyer would inherit, and what support the founder could provide afterward.
My practice also represents revenue-generating SaaS and AI companies, with a preferred range of approximately $1M–$5M ARR. I handle the advisory work personally, but the founder remains essential for demos, technical answers, timely decisions, and transition planning. Attorneys and other qualified professionals handle their respective specialist workstreams.
For new mandates, my usual structure is an upfront engagement fee plus a success fee. The upfront fee reserves my time and covers part of the product review, positioning, materials, research, and initial outreach. It pays for agreed work and committed time; the process can still end without an offer or a sale.
My success fees generally run from 15% to 25%, and can reach 40% for particularly demanding or risky assignments. The proposal reflects the likely transaction size, commercial proof, ownership and preparation, complexity, and how much initial work and risk I am carrying. Fully contingent engagements are rare and considered selectively.
We agree the fee calculation, any minimum, payment timing, and treatment of deferred consideration and earnouts in writing before starting. A lower upfront fee may mean a higher success fee. The engagement needs to leave you with an outcome worth pursuing after fees; I will explain the economics of the specific proposal.
My role is founder-side commercial advisory for qualifying private-company, software, product, and IP sale processes. It covers the acquisition case, buyer research, outreach, preparation for meetings, commercial negotiations, and coordination of diligence and next steps.
The engagement excludes capital raising, minority placements, custody of transaction funds, authority to bind either party, and legal, tax, accounting, securities, or formal valuation advice. Your attorney handles legal advice and transaction documents; qualified tax, accounting, and other professionals handle their respective workstreams.
The written agreement defines my scope for the particular assignment. Ownership, licensing, customer obligations, approvals, and transaction structure should be reviewed by the appropriate professionals. Bring existing buyer discussions and proposed documents to the initial review so responsibilities can be clear before the process progresses.
Confidential initial review
Share what you’ve built, current revenue, and why you’re considering a sale. I’ll review the opportunity personally and tell you whether I see a credible strategic buyer path.
Direct founder review · private reply · selective intake